
Danh mục nội dung
Personal income tax is a tax calculated on an individual’s income sources earned from business activities and other sources such as salaries and wages paid by employers, from capital investments, capital transfer, real estate transfer, prize-winning, copyright, and inheritance gifts. Regardless of Vietnamese or foreigners, depending on residence status, and income level, an individual may have to pay from 5% to 35% of the income earned… Among them, income from salary and wages is the most common and also has the most detailed regulations.
In Vietnam, the deadline for submitting annual tax finalization documents is the last day of the 3rd month from the end of the calendar year or fiscal year.
CASES AUTHORIZED TO FINALIZE PERSONAL INCOME TAX
Employees may not need to carry out tax finalization procedures for income from salaries and wages, but only need to authorize the income payer to carry out this procedure in the following cases:
- Individuals with income from salaries or wages sign a labor contract of 3 months or more at one place and are working there at the time the organization or individual paying the income performs tax finalization including cases of less than 12 working months in a calendar year.
- In case an individual is an employee transferred from an old organization to a new organization due to a merger, consolidation, division, separation, or conversion of the type of business by the old organization or the new organization in under the same system, the individual is authorized to finalize taxes for the new organization.
- Individuals with income from salaries or wages sign a labor contract of 3 months or more at one place and are working there at the time the organization or individual paying the income performs tax finalization including cases of less than 12 working months in a calendar year. At the same time, have current income in other places with an average monthly income of no exceed to 10 million VND in the year and have personal income tax deducted at the rate of 10% if there is no request for tax finalization for this income.
Organizations and individuals paying income from salaries and wages are responsible for declaring tax finalization and finalization on behalf of individuals authorized by the organization or individual paying income, regardless of whether they arise. Tax deduction or no tax deduction. In cases where organizations and individuals do not pay income, they do not have to declare personal income tax finalization.
INDIVIDUALS MUST FINALIZE DIRECTLY WITH THE TAX AUTHORITIES
People with multiple sources of taxable income may not be allowed to authorize the employer but must directly carry out annual finalization procedures with the tax authority, so both the employer and employee need to choose the correct personal income tax declaration and finalization method according to the following cases:
- Work under a contract for more than 3 months in one place and earn an income in another place with an average monthly income of over 10 million/year even though 10% has been deducted.
- Resident individuals have income from salaries and wages paid by organizations and individuals from abroad.
- Resident individuals have income from salaries and wages paid by international organizations, Embassies, and Consulates in Vietnam but have not yet made tax deductions and declare taxes directly to tax authorities quarterly.
PERSONAL INCOME TAX FINALIZATION DOSSIERS
For individuals who declare personal income tax finalization directly with the tax authority
- Personal income tax finalization declaration form 02/QTT-TNCN.
- Appendix list of family deductions for dependents.
- Copies (photocopies from originals) of documents proving the tax amount deducted, temporarily paid during the year, and tax amount paid abroad (if any). In case the income-paying organization does not issue tax deduction documents to the individual because the income-paying organization has ceased operations, the tax authority will base on the tax department’s database to consider and process the finalization dossier. Tax for individuals without requiring tax deduction documents. In case an organization or individual paying income uses an electronic personal income tax deduction document, the taxpayer will use a copy of the electronic personal income tax deduction document (the paper version is printed by the taxpayer and converted from Original electronic personal income tax deduction voucher sent to the taxpayer by the income-paying organization or individual).
- Copy of Tax Withholding Certificate issued by the income paying agency or Copy of bank documents for the tax amount paid abroad with confirmation from the taxpayer in cases prescribed by foreign law, Foreign tax authorities do not issue a certificate confirming the amount of tax paid.
- Copies of invoices and documents proving contributions to charity funds, humanitarian funds, and educational contributions funds (if any).
- Documents proving the amount of money paid by the unit or organization paying income abroad in case the individual receives income from international organizations, Embassies, Consulates and receives income from abroad .
- Dependent registration documents follow the instructions in point a, clause 3, section III of this official dispatch.
For organizations and individuals paying income, the personal income tax finalization declaration dossier is as follows:
- Personal income tax finalization declaration form No. 05/QTT-TNCN
- Appendix detailed list of individuals subject to tax calculation according to the partially progressive schedule, form No. 05-1/BK-QTT-TNCN.
- Appendix detailed list of individuals eligible for tax calculation according to full tax rate, form No. 05-2/BK-QTT-TNCN.
- Appendix detailed list of dependents for family deductions, form No. 05-3/BK-QTT-TNCN.
- In case an individual authorizes an income payment organization to finalize on their behalf, the individual shall prepare a power of attorney for personal income tax finalization for the 2022 tax period according to form No. 08/UQ-QTT-TNCN.
DEADLINE FOR SUBMITTING DOCUMENTS FOR PERSONAL INCOME TAX FINALIZATION
The deadline for submitting tax declaration documents for taxes with annual tax periods is specified as follows:
- No later than the last day of the 3rd month from the end of the calendar year or fiscal year for annual tax finalization dossiers; no later than the last day of the first month of the calendar year or fiscal year for annual tax returns;
- No later than the last day of the 4th month from the end of the calendar year for personal income tax finalization dossiers of individuals directly finalizing taxes;
- No later than December 15 of the immediately preceding year for head tax declaration dossiers of business households and individuals paying tax according to the head tax method; In case of new business households or individuals, the deadline for submitting head tax declaration documents is 10 days at the latest from the date of business commencement.
Thus, the deadline for personal income tax finalization in 2024 is specified as follows:
- No later than March 31, 2024 for annual tax finalization documents.
- No later than May 4, 2024 for personal income tax finalization dossiers of individuals directly finalizing taxes.
NOTES ON PERSONAL INCOME TAX FOR FOREIGN WORKERS:
- A resident individual is a person who meets one of the following conditions: Being present in Vietnam for 183 days or more in a calendar year or for 12 consecutive months from the first day of presence in Vietnam or having permanent residence in Vietnam.
- Depending on whether the individual is a resident or non-resident, they must also declare and finalize personal income tax for income arising in Vietnam or global income.
- Taxable amounts/tax rates between resident and non-resident individuals are completely different. Failure to declare personal income tax clearly and properly will result in fines to tax authorities in subsequent years.
- Resident individuals who have income from salaries and must declare taxes directly at tax authorities include: Resident individuals who have income from salaries paid by international organizations, embassies, and consulates in Vietnam pays but has not yet deducted tax and declares tax directly to the tax authority on a quarterly basis.
- A foreign individual who finishes a working contract in Vietnam declares tax finalization with the tax authority before leaving the country.
- In case an individual has not yet completed tax finalization procedures with the tax authority, he or she must authorize an income-paying organization or other organization or individual to finalize tax according to regulations on tax finalization for individuals. The income-paying organization or other organization or individual receiving authorization for finalization must be responsible for the additional personal income tax amount payable or be refunded the individual’s overpaid tax amount.
Special notes about global income:
- Foreigners residing in Vietnam will have to declare year-end finalization on global income, and pay tax according to a progressive tax schedule from 5% to 35% according to each income level.
- Foreigners who do not reside in Vietnam only have to pay tax at a fixed tax rate of 20% on income earned in Vietnam.
- Income declaration of foreigners in Vietnam must be consistent with:
- Position title, job requirements
- Professional qualifications and work experience
- Cost of living and actual living conditions
- Average income of the country of which the person holds citizenship
- Employer reputation
- Number of days present in Vietnam
- Appointment letter and contents of the labor contract
- The income level declared on the work permit application.
Vietnam’s tax authorities have a management system to identify tax risk cases, thereby applying inspection procedures and tax treaties with most other developed countries to review, which can lead to serious violations, arrears and fines that affect the credit and business history of foreigners in Vietnam.
PERSONAL INCOME TAX RATE
Tax rates and tax calculation for non-resident individuals
- The personal income tax rate for foreigners from salaries and wages of non-resident individuals is determined by taxable income from salaries and wages multiply (x) by a tax rate of 20%.
- Taxable income from salaries and wages of non-resident individuals is determined as income subject to personal income tax for foreigners from salaries and wages of resident individuals.
- Income subject to personal income tax for foreigners from salaries and wages in the case of a non-resident individual working simultaneously in Vietnam and abroad but unable to separate the income arising in Vietnam will be calculated as follows:
a. In cases where foreign individuals are not present in Vietnam:
In which: The total number of working days in the year is calculated according to the regime prescribed in the Labor Code of Vietnam.
b. For cases of foreign individuals present in Vietnam:
Tax rates and tax bases for resident individuals
- The taxable income for PIT for foreigners is determined by the taxable income from business, wages, salaries which are the income that can be evaluated and the tax rate.
- Assessable income is equivalent to taxable income minus (-) the following deductions:
- Family deductions.
- Insurance contributions and voluntary pension funds.
- Charitable, humanitarian and educational contributions.
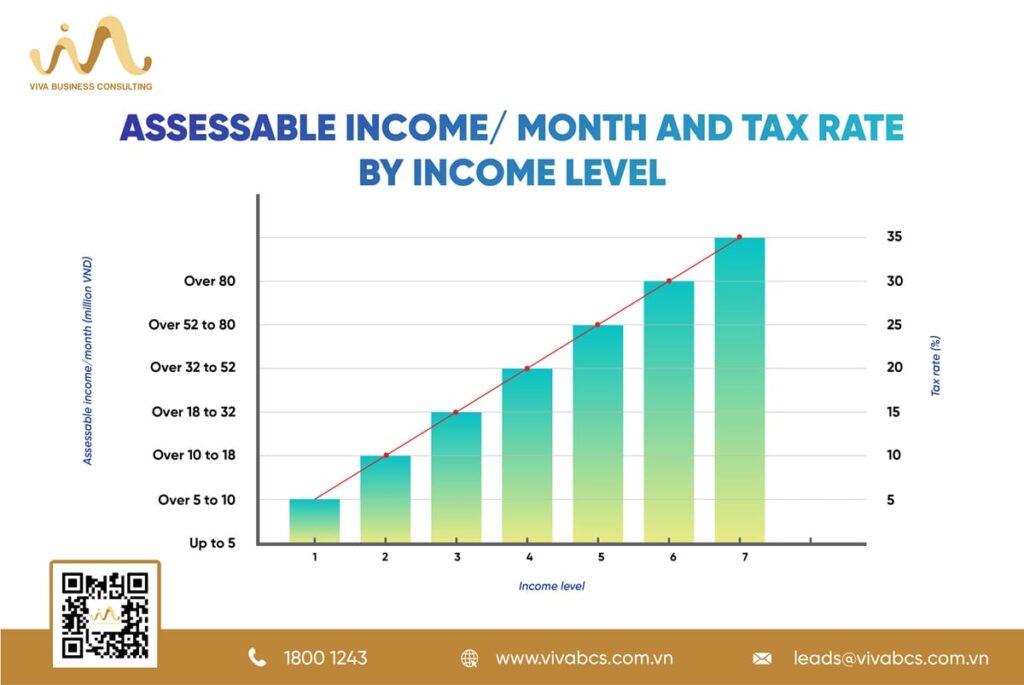
The partially progressive tax schedule is applied to taxable income for income from business, salaries, and wages:
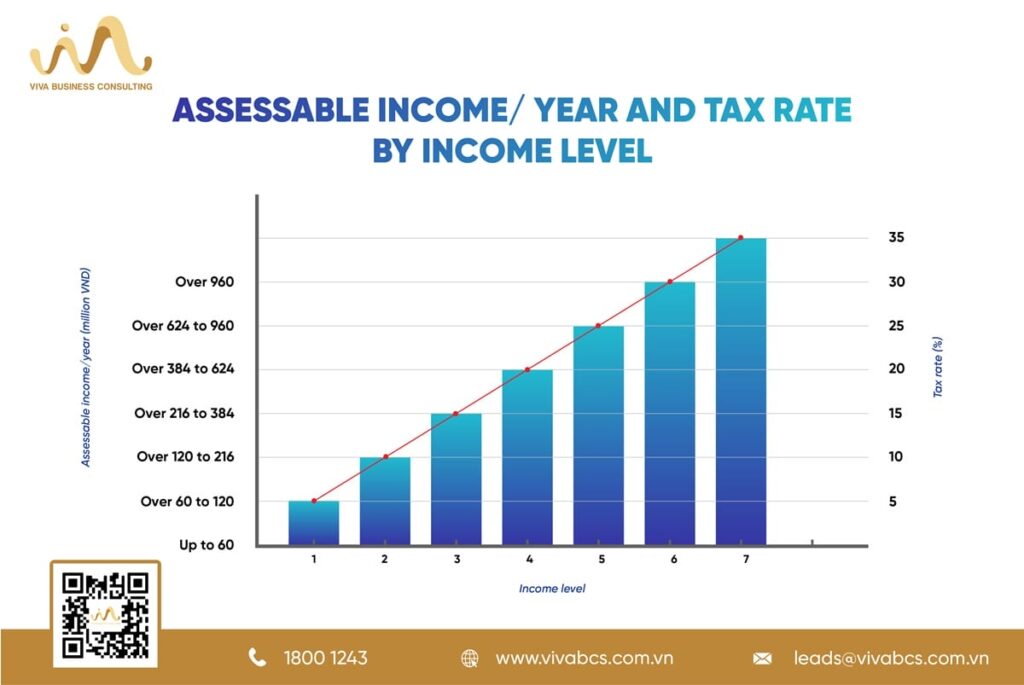
| Tax bracket | Taxable income/year (million dong) | Taxable income/month (million dong) | Tax rate (%) |
| 1 | Up to 60 | Up to 5 | 5 |
| 2 | Over 60 to 120 | Over 5 to 10 | 10 |
| 3 | Over 120 to 216 | Over 10 to 18 | 15 |
| 4 | Over 216 to 384 | Over 18 to 32 | 20 |
| 5 | Over 384 to 624 | Over 32 to 52 | 25 |
| 6 | Over 624 to 960 | Over 52 to 80 | 30 |
| 7 | Over 960 | Over 80 | 35 |
The full tax schedule applicable to taxable income from capital investment, capital transfer, real estate transfer, winning prizes, royalties, franchises, inheritance, and gifts is prescribed as follows:
|
|
|
|---|---|
|
Income from capital investment |
5 |
|
Income from copyrights and franchises |
5 |
|
Income from winning-prizes |
10 |
|
Income from inheritance and gifts |
10 |
|
Income from capital transfer |
20 |
|
Income from securities transfer |
0,1 |
|
Income from real estate transfer |
2 |
BASIC PRINCIPLES OF PERSONAL INCOME TAX FINALIZATION
Declaring, finalizing, and paying personal income tax is very important for both employees and employers, especially year-end finalizaion procedures according to regulations, and will have to comply with the regulations. Basic rules are as follows:
- Resident individuals whose income is generated abroad and who has calculated and paid personal income tax abroad will have the tax amount paid abroad deducted. The amount of tax deducted must not exceed the amount of tax payable calculated according to Vietnam’s tax table calculated for allocation to income generated abroad. The allocation rate is determined by the ratio between the amount of income generated abroad and the total taxable income.
- Resident individuals whose income is generated abroad and who has calculated and paid personal income tax abroad will have the tax amount paid abroad deducted. The amount of tax deducted must not exceed the amount of tax payable calculated according to Vietnam’s tax table calculated for allocation to income generated abroad. The allocation rate is determined by the ratio between the amount of income generated abroad and the total taxable income.
- First tax year: declare and submit final finalization documents no later than 90 days from the date of calculation of 12 consecutive months.
- From the second tax year: declare and submit tax finalization documents no later than the 90th day from the end of the calendar year
- A resident individual who is a foreigner at the end of a working contract in Vietnam shall make tax finalization with the tax authority before leaving the country.
- .For individuals renting houses, land use rights, water surfaces and other assets, personal income tax finalization is required.
- In case an individual declares tax quarterly or declares tax each time it arises for a contract with a payment term of 1 year or less, tax finalization shall be carried out as for business individuals paying tax by declaration method.
- Individuals with income from insurance agents, lottery agents, and multi-level marketing directly finalize taxes with tax authorities if subject to tax finalization.
- Individuals with income from salaries, wages, or business but are considered for tax reduction due to natural disasters, fires, accidents, or serious diseases shall directly settle taxes with the tax authority.
- Individuals and groups of business individuals who do not reside but have a fixed business location in the territory of Vietnam shall declare and finalize taxes as for individuals and groups of business individuals who are residents.
LAWS, DECREES, CIRCULARS GUIDING THE IMPLEMENTATION OF THE LAW ON PERSONAL INCOME TAX EFFECTIVE UNTIL 2024
As of the end of 2024, no new regulations on personal income tax have been added, accordingly, the following regulations will continue to apply:
Personal Income Tax Laws currently effective until 2024:
- Law on Personal Income Tax 2007.
- Law on Amending Tax Laws 2014.
- Law on Amending Personal Income Tax 2012.
- Resolution 954/2020/UBTVQH14 on adjusting the family deduction level of personal income tax issued by the Standing Committee of the National Assembly.
Decrees and Circulars guiding the implementation of the Law on Personal Income Tax currently effective until 2024:
- Decree 91/2014/ND-CP amending Decrees regulating tax.
- Decree 12/2015/ND-CP guiding the Law amending and supplementing a number of articles of the Laws on Taxes and amending and supplementing a number of articles of the Decrees on Taxes.
- Decree 65/2013/ND-CP guiding the Law on Personal Income Tax and the Law amending and supplementing a number of articles of the Law on Personal Income Tax.
- Circular 92/2015/TT-BTC guiding the implementation of value added tax and personal income tax for resident individuals with business activities; guiding the implementation of a number of amendments and supplements to personal income tax stipulated in the Law amending and supplementing a number of articles of the Laws on Taxes 71/2014/QH13 and Decree 12/2015/ND-CP detailing the implementation of the Law amending and supplementing a number of articles of the Laws on Taxes and amending and supplementing a number of articles of the Decrees on Taxes issued by the Minister of Finance.
- Circular 151/2014/TT-BTC guiding the implementation of Decree 91/2014/ND-CP amending and supplementing a number of articles of the Decree on tax issued by the Minister of Finance.
- Circular 119/2014/TT-BTC amending Circulars 156/2013/TT-BTC, 111/2013/TT-BTC, 219/2013/TT-BTC, 08/2013/TT-BTC, 85/2011/TT-BTC, 39/2014/TT-BTC and 78/2014/TT-BTC to reform and simplify tax administrative procedures issued by the Minister of Finance.
- Circular 111/2013/TT-BTC Guiding the Law on Personal Income Tax and Decree 65/2013/ND-CP issued by the Minister of Finance.
- Circular 20/2010/TT-BTC guiding administrative procedures on personal income tax issued by the Ministry of Finance.
- Directive 22/2008/CT-TTg implementing the Law on personal income tax issued by the Prime Minister.
ONE-STOP SERVICE
BUSINESS RECORD MANAGEMENT AND PROCEDURES FOR TAX DECLARATION – FINALIZATION
Our experts will assist you in managing labor relations records, tax compliance reports, declaring according to regulations in the optimal way, helping tax records to be done correctly from the beginning, according to a system of strict procedures:
- Collect and manage taxpayer records and tax records according to each source of income. Review and assist in completing related documents
- Calculate the optimal amount of tax payable for each source of income
- Prepare tax declaration documents for each source of income
- Submit tax returns, annual settlement according to current regulations and support tax payment
- Manage and handle on behalf of any related issues as requested by tax authorities
- Complete documents on labor relations, tax reports, tax finalization, adjustments, explanations, tax refunds… Until you receive a certificate of completion of tax obligations
- Consult on tax planning and optimization for the next year
- Organize the storage and completion of personal income tax records using hard and soft files to serve future comparison and explanation requirements.
Personal income tax regulations and procedures may change from time to time, taxpayers should be consulted by appropriate professional qualifications for each case to ensure compliance and optimization of taxes payable.
We will continuously update new regulations related to the management, declaration and finalization of personal income tax in 2024 and practical applications in each case.
Read more:
- Compulsory social insurance for foreign employees who are working in Vietnam
- Tax management – tax planning in vietnam – properly comply to optimize your long term business
- How to apply for Vietnam e-visa
- Personal income tax in Vietnam – 10 types of taxable income and tax rates
- Personal income tax for foreign employees – methods of declaration and payable amount
- Non-taxable – condition for personal income tax exemption and non-taxable (part 1)
- Non-taxable – condition for personal income tax exemption and non-taxable (part 2)
- Taxable incomes from wages and remunerations
- Personal income tax in Vietnam – notes on your annual personal income tax settlement
- Personal income tax in Vietnam – Annual final procedures
- Expat in Vietnam – the local required compliance procedures by laws – one-stop solution
- Expat in Vietnam – managing the required compliance procedures
- Taxable income and methods of declaration for Expats – personal income tax in Vietnam

